| |||||||||||||||
| Probability Density Function | The general formula for the probability density function of the gamma distribution is where  is the shape parameter,  is the location parameter,  is the scale parameter, and  is the gamma function which has the formula  The case where = 0 and = 1 is called the standard gamma distribution. The equation for the standard gamma distribution reduces to Since the general form of probability functions can be expressed in terms of the standard distribution, all subsequent formulas in this section are given for the standard form of the function. The following is the plot of the gamma probability density function. 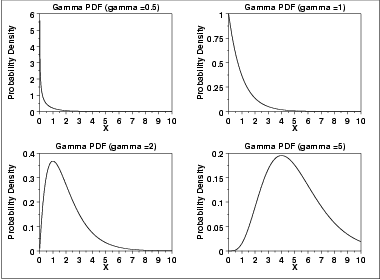 | ||||||||||||||
| Cumulative Distribution Function | The formula for the cumulative distribution function of the gamma distribution is where is the gamma function defined above and  is the incomplete gamma function. The incomplete gamma function has the formula  The following is the plot of the gamma cumulative distribution function with the same values of as the pdf plots above. | ||||||||||||||
| Percent Point Function | The formula for the percent point function of the gamma distribution does not exist in a simple closed form. It is computed numerically.The following is the plot of the gamma percent point function with the same values of as the pdf plots above. | ||||||||||||||
| Hazard Function | The formula for the hazard function of the gamma distribution is The following is the plot of the gamma hazard function with the same values of as the pdf plots above. | ||||||||||||||
| Cumulative Hazard Function | The formula for the cumulative hazard function of the gamma distribution is where is the gamma function defined above and is the incomplete gamma function defined above.The following is the plot of the gamma cumulative hazard function with the same values of as the pdf plots above. | ||||||||||||||
| Survival Function | The formula for the survival function of the gamma distribution is where is the gamma function defined above and is the incomplete gamma function defined above.The following is the plot of the gamma survival function with the same values of as the pdf plots above. | ||||||||||||||
| Inverse Survival Function | The gamma inverse survival function does not exist in simple closed form. It is computed numberically.The following is the plot of the gamma inverse survival function with the same values of as the pdf plots above. | ||||||||||||||
| Common Statistics | The formulas below are with the location parameter equal to zero and the scale parameter equal to one.
| ||||||||||||||
| Parameter Estimation | The method of moments estimators of the gamma distribution are  where  and s are the sample mean and standard deviation, respectively. The equations for the maximum likelihood estimation of the shape and scale parameters are given in Chapter 18 of Evans, Hastings, and Peacock and Chapter 17 of Johnson, Kotz, and Balakrishnan. These equations need to be solved numerically; this is typically accomplished by using statistical software packages. | ||||||||||||||
| Software | Some general purpose statistical software programs support at least some of the probability functions for the gamma distribution. | ||||||||||||||


Correlation Methods Correlation and Covariance Matrices Fisher's z Transformation ( z r ) Pearson Product-Moment Correlation Coefficient (Pearson's r ) Spearman's Rank-Order Correlation Coefficient (Spearman's ρ) Kendall's Rank Correlation Coefficient (Kendall's τ) Correlation and Covariance Matrices You can generate a correlation or covariance matrix from numeric data columns, and have the choice of storing the computation results in an-autogenerated worksheet, or display the results in a table format whose values can be color coded. This method requires multiple numeric data columns whose values should be stored in a single worksheet. An example of a correlation matrix displayed as a color-coded table is shown below. Using Fisher's z Transformation ( z r ) This option is provided to allow transforming a skewed sampling distribution into a normalized format. The theoretical sampling distribution of the corr...

Comments
Post a Comment